
REQUEST THE ANNULMENT
OF YOUR SWISS FRANC MORTGAGE
The first French law firm to obtain in court the annulment of Swiss franc mortgage loans taken out by cross-border borrowers.
DID YOU TAKE OUT A MORTGAGE LOAN IN CHF?
The loan was used to buy property in France
Cross-border worker (Switzerland)
Your income was in Swiss francs when the mortgage contract was signed, but your property assets are in euros
Not a cross-border worker
You have no connection with Switzerland: your income, savings and assets were in euros when the loan contract was signed
When the property is purchased, converting the loan into euros exposes the borrower to several exchange-rate risks
Between October 1, 2007 and today, the Swiss franc has appreciated by about 70% against the euro
This change in exchange rates has led to a proportional increase in the cost, in euros, of Swiss franc property financing
If you have suffered an exchange-rate loss due to the fall of the euro against the Swiss franc, your loan may be annulled
ANNULMENT OF CHF LOANS
Where do things stand?
A ruling of the Cour de cassation of July 12, 2023 and two decisions handed down by the Court of Justice of the European Union in September and October 2023 give new impetus and clarify the following points:
1 Loan contract clauses must enable borrowers to understand how the financial mechanism of a CHF loan works and assess the potential financial losses they could suffer if the euro depreciates against the Swiss franc. Otherwise, they may be held unfair and the loans may be annulled
2 The action to have loan clauses declared unfair is not subject to any limitation period. Borrowers can challenge these unfair terms at any time, including years after their mortgage loans have ended
3 To enable borrowers toassess in concrete terms the economic consequences of a fall of the euro against the Swiss franc, the bank must provide them with numerical simulations clearly describing the impact on the installments or on the capital to be repaid
4 The concept of consumer is an objective criterion. It does not depend on the person’s knowledge of exchange-rate risk
Unfair terms law must therefore protect all borrowers, including those who work in Switzerland and are presumed to know the risks of a Swiss franc loan
Borrowers can take action by asking the competent court to review whether the clauses of their Swiss franc mortgage loan are unfair
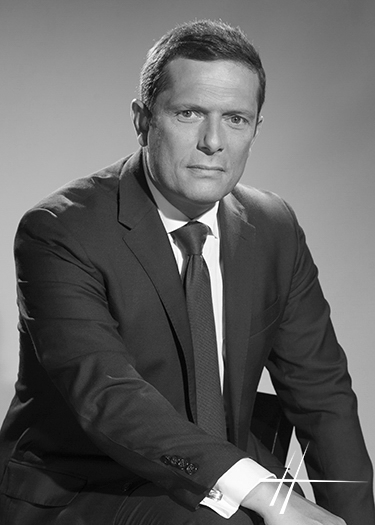
DAVID DANA, ATTORNEY AT THE PARIS BAR
David DANA is an attorney at the Paris Bar.
The firm is dedicated to complex and mass litigation.
Since 2008, he has developed particular expertise in managing and resolving disputes over foreign-currency loans, especially in Swiss francs, granted by French or international banks.
Thanks to this expertise, the firm is able to defend its clients’ interests by offering them the most appropriate legal solutions.
WHAT IF THE LOAN IS ANNULLED?
When buying property in France in euros (EUR) with a loan in Swiss francs (CHF), the borrower is exposed to significant exchange-rate risks.
Let us take a concrete example of a sale of the financed property after the fall of the euro against the Swiss franc:
Purchase price : EUR 350,000
Financing in CHF : CHF 500,000
Exchange rate : CHF 1.42857 for EUR 1
Sale price 5 years later :
EUR 400,000
exchange rate at the time of early repayment :
CHF 1 for EUR 1
Outstanding capital in CHF : CHF 400,000
In this scenario, the borrower will suffer an exchange-rate loss of EUR 120,000
WE ANSWER YOUR QUESTIONS
on the annulment of Swiss franc loans
The Court of Justice of the European Union has laid down transparency requirements for the contractual terms of Swiss franc mortgage loans. The bank must therefore provide the borrower with sufficient and accurate information enabling them to understand how the financial mechanism actually works, so that they can assess the risk of potentially significant adverse economic consequences of such a term on their financial obligations throughout the term of the loan, in the event of a significant depreciation of the euro against the Swiss franc. If the loan terms do not contain this information, they must be held unfair by the court reviewing their clarity. French courts have applied these criteria to Swiss franc loans repayable in that same currency since February 2023
In practice : the borrower must be able to assess the exchange-rate losses they could suffer if the euro falls against the Swiss franc during the term of the loan, by means of numerical simulations provided by the bank. Failing that, the loan must be annulled.
Consumers, that is, those who did not act for the purposes of a business activity, who did not receive an information notice containing a definition of exchange-rate risk, tables with scenarios of adverse CHF/EUR exchange-rate movements and numerical simulations of potential exchange-rate losses (e.g. attached notice).
For non-consumers, that is, professionals, loans cannot be annulled if they were concluded more than 5 years ago. However, the borrower may seek compensation for financial loss in the absence of adequate information on the risk of exchange-rate loss
You must bring the case before the competent courts.
In practice : with the exception of BNP Paribas Personal Finance, banks refuse to annul loans through amicable negotiation.
The Swiss franc loan contract and the purchase contract for the property financed in euros
The risk is the cost of the proceedings (agreed flat fee, costs and disbursements) and an order to pay legal costs under Article 700 of the French Code of Civil Procedure (about EUR 3,000)
If the decision is favorable, the borrower will only have to return the euro equivalent of the capital borrowed, and the bank will be ordered to return the euro equivalent of the principal repayments, interest and fees (and possibly borrower insurance premiums) received under the loan since the start of the contract.
The mutual restitution claims are set off against each other up to the lower amount.
If the borrower has paid more than the initial euro equivalent, the bank will have to refund the excess.
Otherwise, in that case, the borrower will have to pay the balance. Note: if the annulment only reduces the outstanding capital owed to the bank (e.g. from EUR 350,000 to EUR 150,000) and that amount remains significant (e.g. EUR 100,000 or more), you must be able to pay it a few months after the favorable decision, including if it is handed down at first instance within 12 to 18 months.
If the decision is favorable, the bank should be ordered to pay your legal costs under Article 700 of the French Code of Civil Procedure, i.e. about EUR 3,000 per instance.
Proceedings begin with a claim before the competent Judicial Court, which is the court of first instance. They last about 12 to 18 months. The losing party may decide to appeal to the Court of Appeal, the higher court. An appeal is a new set of proceedings that may last a further 12 to 18 months or so. The appellate ruling may be challenged before the Cour de cassation by the party that loses on appeal. In that case, the review of the appeal takes about 12 months.
A favorable decision must be enforced immediately, even at first instance, despite any pending appeal (to the Court of Appeal or the Cour de cassation).
A flat fee covering fees, costs and disbursements is set for each set of proceedings
A success fee is added to these flat fees
In practice : you can call on the legal protection cover included in your home insurance. Depending on the scales, the cover is about EUR 1,000 per instance. Several legal protection policies may be taken out, subject to Article L. 121-4, paragraph 4, of the French Insurance Code.
ESTIMATE THE POTENTIAL GAIN FROM LEGAL ACTION
the steps
1. Confidential information to provide
We will ask you to provide confidential information (GDPR) about your loan. (time – 5 minutes)
2. Approximate estimate of your potential gain
After a short questionnaire, you will receive an approximate estimate of the potential gain from legal action (time – 5 minutes)
3. Webinar registration
You can register for a webinar to better understand how legal action over your Swiss franc loan works and what is financially at stake, such as the length of the proceedings, the legal arguments that will be raised and developments in European and French case law.
4. Video meeting
If you would like more information, an interview will be arranged by videoconference. The fees, costs and disbursements per instance will be given to you at the end of this free meeting.
5. Legal proceedings
A fee agreement covering fees, costs and disbursements and an engagement letter will be sent to you beforehand, setting out the terms of our engagement.